Articles & Toolkit > Every Business Has Risk — Resilient Businesses Manage It Well
Every Business Has Risk — Resilient Businesses Manage It Well
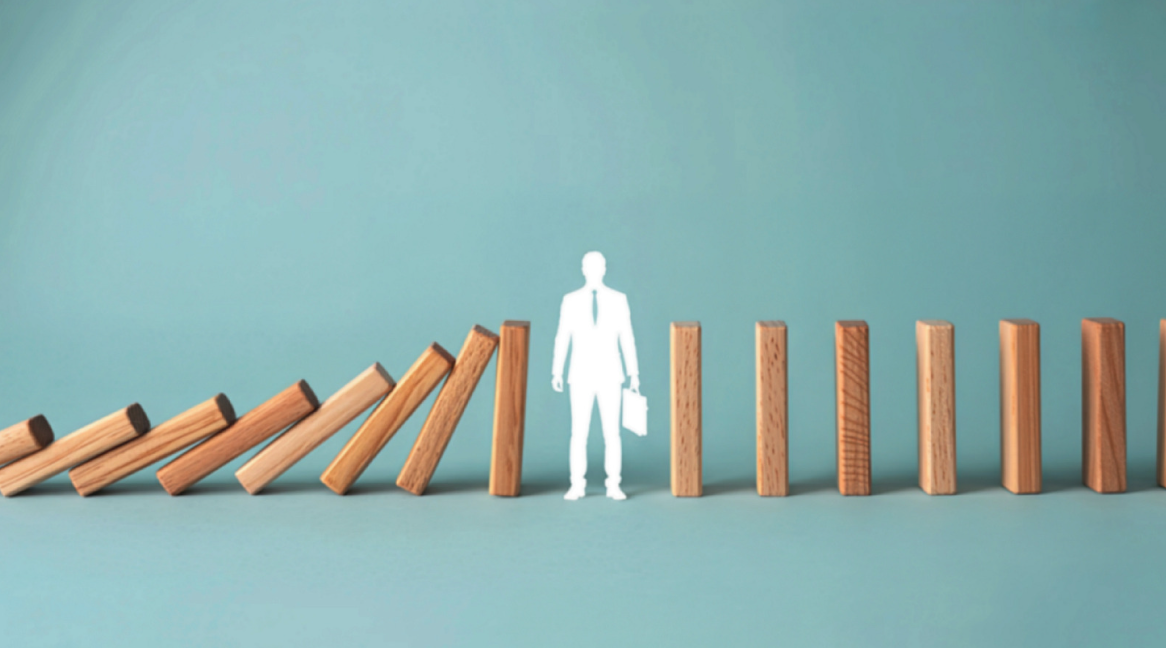
Risk is an unavoidable part of doing business. Every decision to employ someone, extend credit to a customer, invest in equipment, introduce new technology, enter a new market or rely on a supplier carries some degree of uncertainty. Even choosing not to act can create risk if competitors, customer expectations or economic conditions continue to change around the business.
Yet risk management is sometimes approached as though its purpose is to eliminate uncertainty altogether. For smaller and growing businesses in particular, the term can evoke complex risk registers, corporate governance frameworks and compliance exercises that seem far removed from everyday operations.
In practice, effective risk management is much more fundamental. It is about understanding what could materially affect the business, considering how exposed the organisation is, and deciding what should be done about it. The objective is not to create a business in which nothing can go wrong. Such a business does not exist. The objective is to create one that is less likely to be surprised by foreseeable problems and better equipped to respond when unexpected ones arise.
Resilience does not come from avoiding every risk. It comes from understanding which risks matter, managing them deliberately and maintaining the capacity to respond when circumstances change.
Risk Exists in Every Business
Some risks are immediately visible. A major customer could leave, a supplier could fail to deliver, equipment could break down or an economic downturn could reduce demand. Others develop gradually and may be harder to recognise. Profit margins can erode over time, key employees can become increasingly difficult to replace, outdated systems can create inefficiencies, or a growing business can slowly become dependent on a small number of customers without leadership fully appreciating the concentration.
There are also risks created by success itself. Rapid growth can place pressure on cashflow, systems and employees. New technology can improve productivity while introducing cyber security or governance concerns. Expanding the team can increase capability while creating a greater need for delegation, internal controls and documented processes.
Risk is therefore not limited to businesses experiencing difficulty. Healthy and growing organisations face risk as well; the nature of that risk simply changes as the business evolves.
Recognising this is important because risk management should not be reserved for moments of crisis. By the time a risk has become an urgent problem, the range of available responses may already be narrower and more expensive.
The Risks That Matter Are Not Always the Most Obvious
One of the challenges of risk management is determining where attention should be directed. Businesses face countless uncertainties, and attempting to prepare for every conceivable event would be impractical.
Effective risk management requires prioritisation.
A useful starting point is to consider both the likelihood of an event occurring and the potential consequence if it does. A relatively common problem with limited financial impact may be manageable through routine processes, while a less frequent event capable of seriously disrupting the business may justify considerably greater preparation.
This is where context matters. The same risk can have very different consequences for different organisations. Losing a customer representing two per cent of annual revenue is not equivalent to losing one representing forty per cent. A temporary system outage may be inconvenient for one business but prevent another from operating entirely.
Risk should be considered not only in terms of what could happen, but what it would mean for this particular business if it did.
That perspective helps leadership focus resources on the exposures capable of materially affecting financial performance, operations, reputation or continuity.
Financial Risk Often Develops Quietly
Financial risk does not always arrive as a sudden crisis. More often, it develops gradually through a series of smaller pressures.
Customers begin taking longer to pay. Inventory increases faster than sales. Labour costs rise while prices remain unchanged. Debt commitments grow. Margins narrow by a few percentage points. Tax obligations accumulate without sufficient cash being set aside.
Individually, each development may appear manageable. Collectively, they can significantly weaken financial resilience.
This is one reason regular financial reporting matters beyond measuring historical performance. Good reporting can help management identify changes in margins, cashflow, working capital and cost structures before those changes become severe.
Forecasting can add another layer of visibility by considering what current trends may mean for the months ahead. If a business can see that cashflow is likely to tighten in six months, it has time to review expenditure, reconsider investment plans, improve debtor collection or investigate funding options. Discovering the same issue when the bank balance is already under pressure creates a very different decision-making environment.
Financial visibility is one of the most practical forms of risk management because problems are generally easier to address while there is still time to choose how to respond.
Concentration Can Create Hidden Vulnerability
Successful businesses often develop around what works. A valuable customer relationship grows, a reliable supplier becomes the preferred source of critical products, or one service becomes responsible for a substantial proportion of revenue.
There is nothing inherently wrong with concentration. Long-term relationships can be commercially valuable and specialisation can create competitive advantage. The risk arises when dependence becomes significant without being recognised.
Customer concentration is a common example. A large customer may be profitable, reliable and important to the business, yet losing that customer could still create significant disruption. The same principle applies to suppliers, distribution channels, products, geographic markets and even individual employees.
Managing concentration risk does not necessarily mean ending successful relationships simply to achieve diversification. It means understanding the dependency and considering whether contingency plans are appropriate.
If one supplier is critical, is there an alternative? If one customer represents a significant proportion of revenue, how would the business respond if that relationship ended? If one employee holds essential technical knowledge, is that knowledge documented and shared appropriately?
Awareness turns an unrecognised dependency into a risk that can be managed.
People Can Be Both an Organisation's Strength and a Source of Dependency
Every business depends on people, but smaller organisations can be particularly vulnerable to key-person risk. Founders may hold most major customer relationships, senior employees may understand systems nobody else knows how to operate, and experienced team members may carry years of organisational knowledge that has never been documented.
These individuals may be exceptionally capable. That is precisely why dependence on them can become significant.
If a critical employee resigns, becomes unavailable or changes roles, the organisation may suddenly discover how much knowledge or authority was concentrated with one person. The consequences can include operational disruption, delayed decisions, customer dissatisfaction and additional pressure on the remaining team.
Reducing key-person risk is not about making people less valuable. It is about ensuring the business itself retains sufficient capability. Documented processes, succession planning, cross-training and appropriate delegation can help distribute knowledge while allowing experienced employees to contribute at a higher level.
This also supports healthier organisations. When one person believes they can never take leave because nobody else knows what they do, the arrangement is risky for both the individual and the business.
Technology Changes Risk Rather Than Removing It
Technology has significantly reduced some traditional business risks. Cloud systems improve access to information, automation can reduce manual processing and integrated platforms can create greater efficiency and visibility.
At the same time, technology introduces different forms of exposure.
Businesses increasingly depend on digital platforms, online banking, cloud-based information and automated processes. Cyber security incidents, system outages, inappropriate access, incorrect automation rules or poor data management can therefore have substantial operational and financial consequences.
Artificial intelligence adds another dimension. These tools can improve productivity and provide valuable assistance, but their outputs still require appropriate judgement, governance and review. Automation does not transfer accountability from the organisation to the technology.
This makes digital governance increasingly relevant even for relatively small businesses:
Who has administrator access?
What happens when an employee leaves?
Are critical systems protected appropriately? Are backups available?
Who reviews automated outputs or changes to important workflows?
Technology can reduce operational effort, but it does not remove the need for oversight. It changes where that oversight needs to occur.
Internal Controls Protect More Than Money
Internal controls are sometimes viewed primarily through the lens of fraud prevention. While that is an important purpose, their value extends much further.
Appropriate controls can reduce errors, clarify responsibilities, improve financial reporting and protect employees from being placed in situations where too much authority rests with one individual. They also create clearer evidence of how important transactions and decisions were handled.
For example, separating payment preparation from payment authorisation can reduce both fraud and accidental error. Reviewing changes to supplier banking details can help prevent incorrect or fraudulent payments. Regular bank reconciliations can identify discrepancies before they remain unresolved for months.
The appropriate controls will differ according to the size and complexity of the business. A small organisation should not attempt to reproduce the governance structure of a large corporation, but simplicity should not mean an absence of oversight.
Good controls are proportionate. They focus attention where consequences are meaningful without creating unnecessary administrative burden.
Risk Management Should Support Decision-Making, Not Prevent It
Poorly designed risk management can become excessively cautious. If every uncertainty is treated as a reason not to proceed, risk management begins to restrict the very activities that allow businesses to grow.
Businesses need to take risk. Hiring employees involves risk. Investing involves risk. Entering a new market involves risk. Extending credit, developing a product and adopting new technology all involve uncertainty.
The role of risk management is therefore not to say no to every uncertain decision. It is to help leadership make those decisions with a clearer understanding of what is at stake.
An investment may still proceed after risks are identified, but perhaps in stages rather than all at once. A new customer may receive credit, but within an appropriate limit. A new system may be introduced after access controls, implementation responsibilities and contingency arrangements have been considered.
Good risk management creates informed confidence rather than unnecessary caution.
That is an important distinction because organisations that understand their risks may actually be better positioned to pursue opportunities. They know where their vulnerabilities lie and can make decisions accordingly.
Scenario Planning Makes Risk More Tangible
Some risks remain abstract until leaders consider what they would mean in practical terms. Scenario planning can help bridge that gap:
What would happen if revenue fell by fifteen per cent for six months?
How long could the business continue meeting its commitments?
What if its largest customer left?
What if a critical supplier could not deliver for eight weeks?
What if the owner were unexpectedly unavailable for a month?
These questions are not intended to encourage pessimism. They help expose assumptions.
A business may discover that it has adequate cash reserves but significant customer concentration. Another may have diversified revenue but rely heavily on one operational employee. A third may be financially healthy but have no clear response if its primary technology platform becomes unavailable.
Scenario planning can also consider positive risks. What happens if demand increases by thirty per cent? Can the business fund the additional working capital? Does it have enough people and operational capacity? Could rapid growth place pressure on customer service or financial controls?
Risk exists on both sides of uncertainty. Businesses need to be prepared not only for disruption, but also for opportunities that arrive faster than expected.
Risk Management Is an Ongoing Leadership Responsibility
A risk assessment completed once and placed in a folder has limited value because businesses do not remain static. Customers change, employees leave, technology evolves, economic conditions shift and new regulations emerge.
Risk management therefore needs to be part of ongoing leadership conversations.
This does not necessarily require a lengthy formal exercise every month. For many businesses, it may simply mean regularly asking whether material exposures have changed, whether existing controls remain appropriate and whether new decisions create dependencies that need to be understood.
Financial reporting can contribute to those conversations by highlighting changes in margins, cashflow, debtors or costs. Operational reporting may reveal customer concentration, employee capacity or supplier issues. External developments may introduce risks that did not exist previously.
Leadership is responsible for connecting these signals.
The most useful risk management is not separate from running the business. It is part of how the business is run.
Resilience Is Built Before It Is Tested
There is a common characteristic across many forms of business risk: preparation is considerably easier before the problem occurs.
Cash reserves are easier to build during profitable periods. Alternative suppliers are easier to investigate before the primary supplier fails. Processes are easier to document while experienced employees are still available. Cyber controls are easier to strengthen before an incident. Customer concentration is easier to address before a major relationship ends.
Once a crisis begins, leadership attention shifts towards immediate response and the number of available options often reduces.
This is why resilience is rarely created during the crisis itself. What becomes visible during difficult periods is often the result of decisions made much earlier.
Businesses that maintain financial discipline, understand their dependencies, develop capable people and establish appropriate controls may still experience disruption. The difference is that they are more likely to have the capacity to absorb it and respond thoughtfully.
Final Thoughts
Every business has risk. The presence of risk does not indicate that a business is poorly managed, just as growth and success do not make an organisation immune from uncertainty.
What matters is whether significant risks are understood.
Resilient businesses recognise that financial pressure, customer concentration, key-person dependency, technology, operational processes and changing market conditions can all affect their ability to perform. They do not attempt to eliminate every possibility of something going wrong. Instead, they identify the exposures that matter, establish proportionate controls and create enough financial and operational flexibility to respond when circumstances change.
This approach does more than protect the organisation from downside. It can also improve decision-making, strengthen governance and give leaders greater confidence when pursuing opportunities.
Risk is part of doing business. Resilience comes from ensuring that uncertainty does not automatically become vulnerability.
The businesses best prepared for the future will not necessarily be those that encounter the fewest challenges — they will be those that have developed the visibility, discipline and capacity to manage those challenges without losing sight of where they are going.
At Shepherdson & Company, Your Success Is Our Business
Your business is unique — and so are your goals. If this article has raised questions or sparked ideas for your business, we’d be happy to help. Reach out here to start the conversation.
Discover More Resources